Showing posts with label Robert Kiyosaki. Show all posts

Tuesday, February 11, 2020

Do You Want To Be Rich?

This post originally appeared on the Hermit Haus Redevelopment website on 2020-02-04.
I think it is better to be wealthy than rich. Scales from Shutterstock
This T-shirt captures two popular memes. I can’t make up my mind if it’s brilliant or indecisive. Photo source: Teepublic
Robert Kyosaki in front of his cash flow quadrants. Oddly enough, people in the Self-employed and Business quadrants can have a harder time achieving financial independence than those in the Employee quadrant because of higher lifestlye expectations. Society doesn’t expect janitors to shell out for a new luxury car every couple of years. Electricians aren’t expected to have a collection of Lucchese boots. Doctors and small business owners often face those expectations.
I’m in the high-fidelity first class traveling set
I think I need a Lear jet

—Roger Waters

Only you can define your own success, and only once you have defined it can you establish the long-term and interim goals to get you there. So in that spirit, let me ask you a question.
Do you want to be rich?
Not me. I’d rather be wealthy.
When I make that argument, it’s not just semantics. I firmly believe being rich and being wealthy are synonymous only in the broadest sense of the terms. In fact, trying to become rich can be an obstacle to becoming wealthy. Here’s why, being rich is having the appearance of being wealthy. The price you pay for that appearance can prevent you from ever having actual wealth. In appearing to be rich, you spend money on things that make you appear rich. Since you can only spend that money once, it does not go to building your wealth.
In other words, appearing to be rich takes money out of your pocket. Being wealthy generates income, whether you work for it or not.
Spending money is a drug. It releases endorphins in the brain. Endorphins work like morphine or codeine, and they can be just as addictive. When you buy new clothes, the endorphins create a rush of good feelings. People can come to depend on that rush. But as with other drugs, that relief is fleeting and illusory. Soon, instead of making them feel better, people are shopping to get that rush just so they don’t feel bad.
Buying new clothes or accoutrements is not a problem. Buying them when you can’t afford them, or even when you don’t need them is. I know people who spend several hundred dollars a month on clothes. If their wealth generates that kind of income, more power to them. If their jobby job creates the income for this spending or worse, if they can’t afford it, it’s a real problem that can prevent them from ever accumulating the wealth that could make such spending sustainable. Looked at another way, a $500 a month clothes habit, amounts to $6,000 a year. Depending on your market, that’s a downpayment on a rental house every one to three years. The rental house could net you as much as $500 a month in ongoing income.
Cars have always been my weakness in this area. For most of my adult life, a Jaguar XJ has always been my dream car. I bought a used one in the 1980s, but I had to sell it when the cost of maintenance became unsustainable. When I finally bought a new one, I thought I’d finally made it. I felt great driving it around. But as Stephen West observes, “…what actually happens is you get the dream car…then it just becomes…your car at a certain point. Then inevitably…there’s something else that you’re desiring every day.” We are “constantly restlessly striving for things in a perpetual state of discontent.”
That is the real trap of things. They don’t make us happier. They just keep us from being independent. We get caught in the webs of excess consumerism and conspicuous consumption. That Jaguar is a perfect example. At the time, I could have bought a rent house for what I paid for it. In Austin, that rent house would be worth about 140% of its purchase price. If I were to sell the Jag, it would bring about 15% of its purchase price. And clothes are worse. Sometimes we can’t even give away old clothes.
Consumerism is the bonfire into which we throw our hard earned money…and our financial independence. Spending money on mere things may make us feel good at the time—it really does—but it makes someone else wealthy at our expense.
So when you go to the store and find yourself about to spend money, take a second to ask yourself, “What does this purchase help me accomplish?”
Do you need that Lear Jet, or just want one?

Tuesday, April 12, 2016

Entrepreneurial Blues

A good entrepreneur finds balance. Image by: Bitmoji
This post originally appeared on the Hermit Haus Redevelopment website on 2016-04-05.
Warning: This post can be construed as whining. If I hadn’t promised to be as honest as possible about our journey, I wouldn’t post it. It sounds like whining to me, and I don’t like whining. Feel free to skip it. But if you want to know what it’s really like to run a small real estate redevelopment company, I guess I’m writing this for you.
When you’re getting started—and possibly even after you’ve been doing redevelopment work for awhile—you don’t have a huge staff to rely on. Some of the many tasks required to keep a company like this one working include but are not limited to the following (presented in no particular order):
  • Finding money
  • Budgeting
  • Plowing through the MLS
  • Prospecting for buyers, sellers, contractors, handymen, etc.
  • Reviewing contracts
  • Signing contracts to buy, sell, and finance projects
  • Keeping the books
  • Finding money
  • Monthly, quarterly, and annual financial reporting
  • Paying contractors, assistants, lenders, suppliers, etc.
  • Communications (blogging, Facebook posts, one-off letters, advertising, etc.)
  • Marketing, marketing, and marketing
  • Crunching numbers
  • Estimating repairs
  • Finding just the right wine
  • Finding money
  • Managing contractors and vendors
  • Setting policy and defining procedures
  • Negotiating with buyers, sellers, contractors, suppliers, etc.
  • Record keeping (physical and electronic documents like permits, licenses, contracts, etc.)
  • Envisioning, inspiring, and directing operations
  • Finding just the right whine
I believe in job creation, but I also believe in profits. So there are only four of us working on this enterprise, and we each have unique roles and skills. To oversimplify: Russell works on finding deals and keeping the back-end systems running. Carol is our real estate guru; she keeps all of our preliminary numbers realistic, is our numero uno marketeer, and manages projects. Sue Ann is our social media expert, editor in chief, and networker. That leaves most of the boring business stuff to me. I love what I do, but...whine!
We do have assistants—virtual and otherwise—who handle most of our secretarial work: printing, copying, and mailing marketing materials. But the other listed tasks (and many, many more) fall to one of the four principle investors.
What set off this whine-arama is that I spent almost my whole day for the last two days chasing down random bits of paperwork for lenders and title companies involved in two of our current projects. In a perfect life, this would have been work I delegated to a file clerk. Unfortunately, I am the file clerk (technician level, in Kiyosaki’s quadrants).
Now you learn in investor school to prepare for this by keeping the most commonly needed documents in a folder on your desktop. This I do. However, each transaction we do adds to that list of documents. My “Commonly Needed” folder now runs just over 8MB, compressed. I’m waiting for some bank or title company technician to balk at looking though it and ask, “Why don’t you just send me the documents I need?” But so far, they always find just one more document to request.
My advice: Keep smiling and telling yourself it’s all a brilliant learning exercise that you’ll get through and eventually have it all down and a staff to delegate it to. That or learn to “play the guitar on MTV.”

Saturday, February 27, 2016

Starting the Journey to Freedom

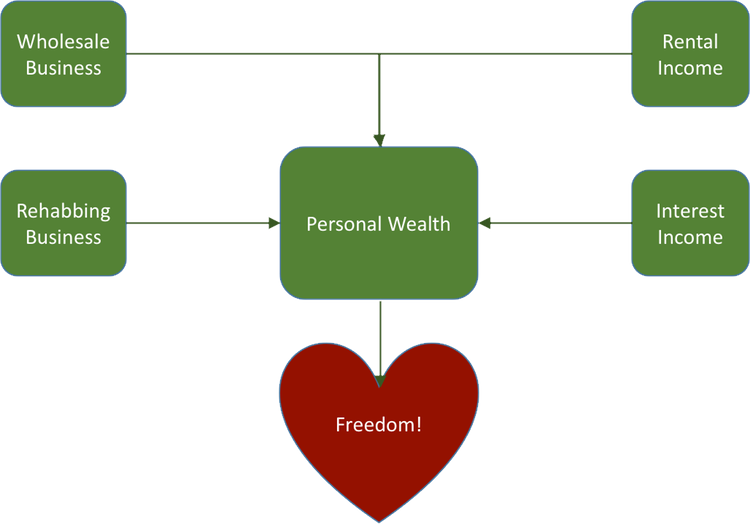
A very complex graphic A balanced approach to investing can help you achieve the goal of personal freedom—whatever that means to you.
This post originally appeared on the Hermit Haus Redevelopment website on 2016-02-25.

I’ve gotten several questions about the cash flow diagram in my last post, so I’m going to explain it in detail today.

First, if you haven’t already read Robert Kiyosaki’s short book Rich Dad, Poor Dad, I highly recommend it. I even bought copies for many of my friends and team members. It’s a short read, but it packs a lot of financial intelligence in amongst its folksy yarn. It’s not biography (or necessarily factual), but the fictive stories illustrate his points.

Kiyosaki categorizes income into two income families, each of which comprise two types of people:

Robert Kyosaki in front of his cash flow quadrants. Kiyosaki’s Quadrants
Active Income
  • Employees (E) have a job and work for someone else.
  • Self-employed persons (S) have a job but work for them selves.
Passive Income
  • Business owners (B) have a system that employs other people’s time, energy, and intelligence to generate income without requiring the business owner’s direct input.
  • Investors (I) put their money to work to make more money.

If you look closely at these two graphics, you’ll see how they align. Real estate wholesaling and redevelopment are essentially forms of employment or self-employment. If you don’t work at them, the income goes away. Rental and interest income are more passive, but managing rental properties can become a jobby-job. Ask me how I know.

That said, you could turn your active businesses more passive by employing enough people to minimize your active effort in them. That’s the goal, isn’t it?—to have the business create the income you use to buy your way out of it.

These are lessons I’m still working on. It’s very easy for me to get down into the weeds of my investments until managing them takes so much time I’m not creating new opportunities. Moving from the left side of the graphics to the right requires a real shift in mindset. It requires stepping away from the illusion of security into the security that comes from understanding how money works and how to make it work for you. That’s not an easy transition, but at least I can see where I’m going.

The goal of any income stream should be wealth creation. Wealth eventually becomes self-sustaining, unless you gamble it away or try to live above the means it provides. When wealth becomes self-sustaining you have achieved a goal most of us only dream of: freedom.


Wednesday, February 03, 2016

Taxes

Bitmoji cartoon of me getting a tooth knocked out Taxes hurt, especially when you can’t plan for them. Photo source: Bitmoji
Let me tell you how it will be
There’s one for you, nineteen for me
‘Cause I’m the taxman, yeah, I’m the taxman

George Harrison

I got a property tax bill in the mail today from DeWitt County for the Yorktown farm. Property taxes in Texas are usually due by the end of January. This is February. Surprise!!

Without going into too much detail, let me just say that the bill is well into the five digit range. And because they would normally have been due a few days ago, I just took advantage of an investment opportunity, so I don’t have that kind of free capital. I don’t like to let my money be anywhere near as lazy as I am. I want it to work for me.

Theodora on her broom “I’ll get you…and your little dog, too. You’ve got to pay your taxes. Pay! Pay!” Photo source: Villains Wikia

There are a couple of bright spots on this dung heap. First, the county admits they were late getting the tax bills out (because they were “understaffed,” they said—whose fault is that?). Because of that, they are allowing until the 27th to pay the taxes “without penalty.” That would be nice if people (other than my dad) left that kind of money lying fallow in a moldy bank account somewhere. Now I have to find it.

The real bright spot is that I “paid myself first,” as Robert Kiyosaki puts it. I put my money to work in an investment that will earn far more than the penalties I’ll incur for paying the property tax late. And since there are a half dozen separate bills, I can string the county out paying them off over time as more money come is.

This situation worked out much better than if I had paid the taxes before the opportunity came along.